A regional bank was losing younger depositors and small-business owners to neobanks because opening a checking account still required branch paperwork and three business days of manual back-office KYC checks. Using the strangler-fig pattern, SNWN built high-speed REST/gRPC microservices around the legacy core ledger and launched a native mobile onboarding flow with live biometric ID verification. New accounts now open and fund in 3 minutes 40 seconds, lifting monthly sign-ups by 2.8x.
Why Young Customers Dropped Off Before Finishing Sign-Up
Marketing campaigns drove thousands of downloads to the bank's mobile app each month, but the moment new users tapped 'Open an Account', the app kicked them out to a mobile browser PDF upload form and told them to wait 72 hours for an email.
Key Operational Bottlenecks Before the Project
- 68% of prospective customers abandoned sign-up when asked to print, sign, or wait days for manual ID review.
- The bank's 20-year-old core ledger accepted only brittle SOAP XML calls and locked up during evening batch windows.
- Compliance teams spent hours manually cross-checking utility bills against AML and sanctions watchlists.
How We Modernized Onboarding Without Risking the Core Ledger
Replacing a bank's core ledger takes years and carries huge risk. Instead, we built a fast, resilient API facade in front of it and automated identity checks end to end.
Built a Strangler-Fig API Gateway Over Legacy SOAP Interfaces
We created clean, versioned Java/Spring Boot microservices with Redis caching and event sourcing so mobile apps get sub-150ms JSON responses even when the underlying core ledger runs nightly settlement batches.
Integrated Live Liveness Biometrics, Government ID OCR, and Instant AML Checks
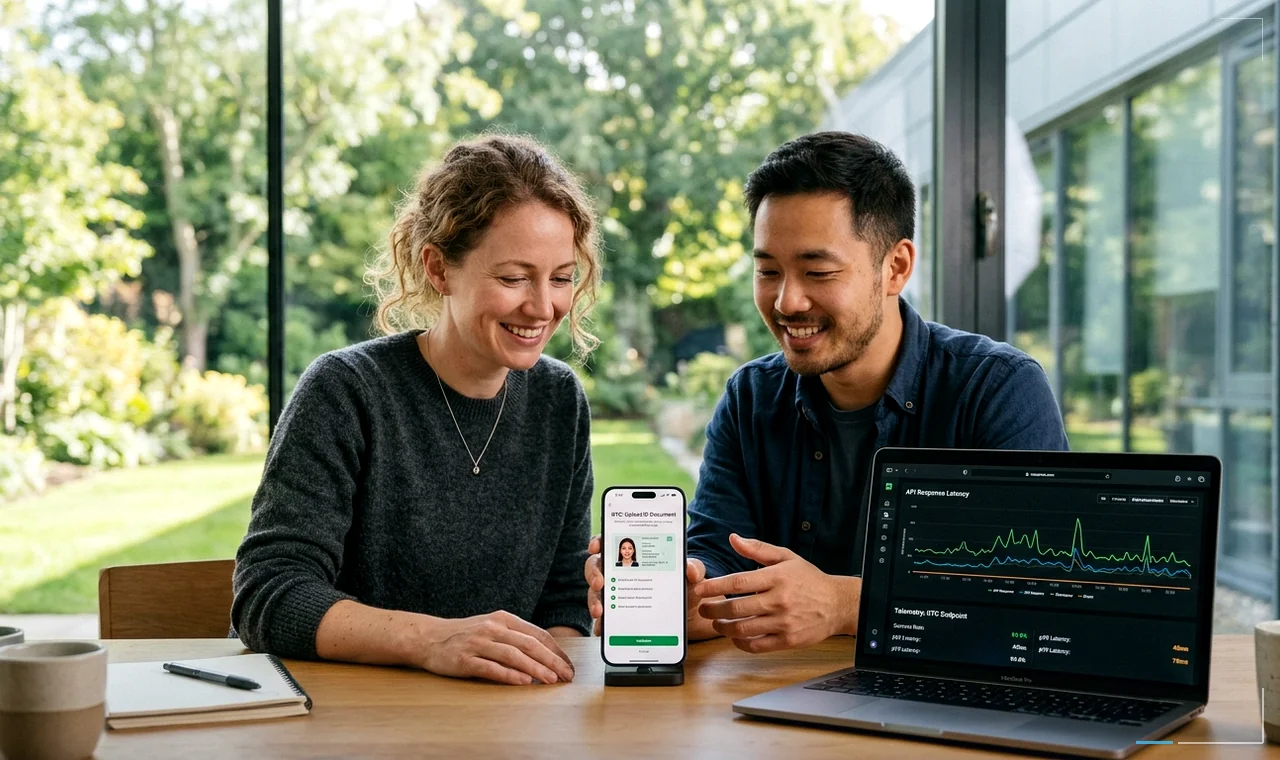
Applicants snap their ID card and record a two-second liveness selfie inside the native app. Automated KYC/AML orchestrators verify document authenticity and screen sanctions lists in under 12 seconds, routing only rare edge cases to human compliance officers.
Added Instant Virtual Debit Card Provisioning for Apple Pay and Google Pay
The moment KYC clears, our card-issuing microservice generates a tokenized virtual debit card so the customer can fund their account via instant transfer and tap-to-pay right away before the physical card arrives in the mail.
Hardened Mobile App Security with Device Binding and mTLS Pinning
We enforced certificate pinning, hardware enclave key storage, behavioral fraud scoring, and continuous VAPT penetration testing prior to public rollout.
3m 40s Onboarding and Nearly Triple Monthly Funded Accounts
App Store ratings climbed from 3.1 to 4.8 stars within two quarters, and compliance officers now review only the 6% of applications that genuinely need human judgment.
Median Time to Active Account
Down from 3 business days of manual document queues and branch callbacks.
Increase in Funded Sign-Ups
Same paid marketing budget now converts nearly three times more active depositors.
Straight-Through KYC Rate
Clean applications clear ID, liveness, and AML checks automatically with full audit logs.
Day-to-Day Business Impact
- 61% of newly onboarded customers make their first mobile wallet transaction within 24 hours of sign-up.
- Zero core-ledger downtime during evening batch windows thanks to asynchronous ledger-sync queues.
- Passed external banking penetration tests and central-bank eKYC compliance review on schedule.
Tools, Platforms, and Technologies Used
Every component in this deployment was selected for long-term stability, clear observability, and straightforward handover so internal engineers never get locked into black-box scripts.
Microservices & Banking APIs
See how our specialists design, migrate, and manage workloads like this every day.
Frequently Asked Questions About This Project
How does the mobile app stay online when the legacy core banking system runs nightly batches?
An event-sourced shadow ledger and Redis read-cache serve balances and accept new account applications 24/7, syncing confirmed transactions cleanly to the legacy core as soon as its batch window reopens.
Does automated mobile KYC meet strict banking AML and anti-spoofing regulations?
Yes. Passive 3D liveness checks block printed photos, screen replays, and deepfakes, while every AML/PEP watchlist score and document hash is stored immutably for regulatory inspection.
How long did it take to launch the first production pilot?
Employees and invite-only beta users opened real funded accounts in week 9, followed by full public App Store and Google Play release in week 14.